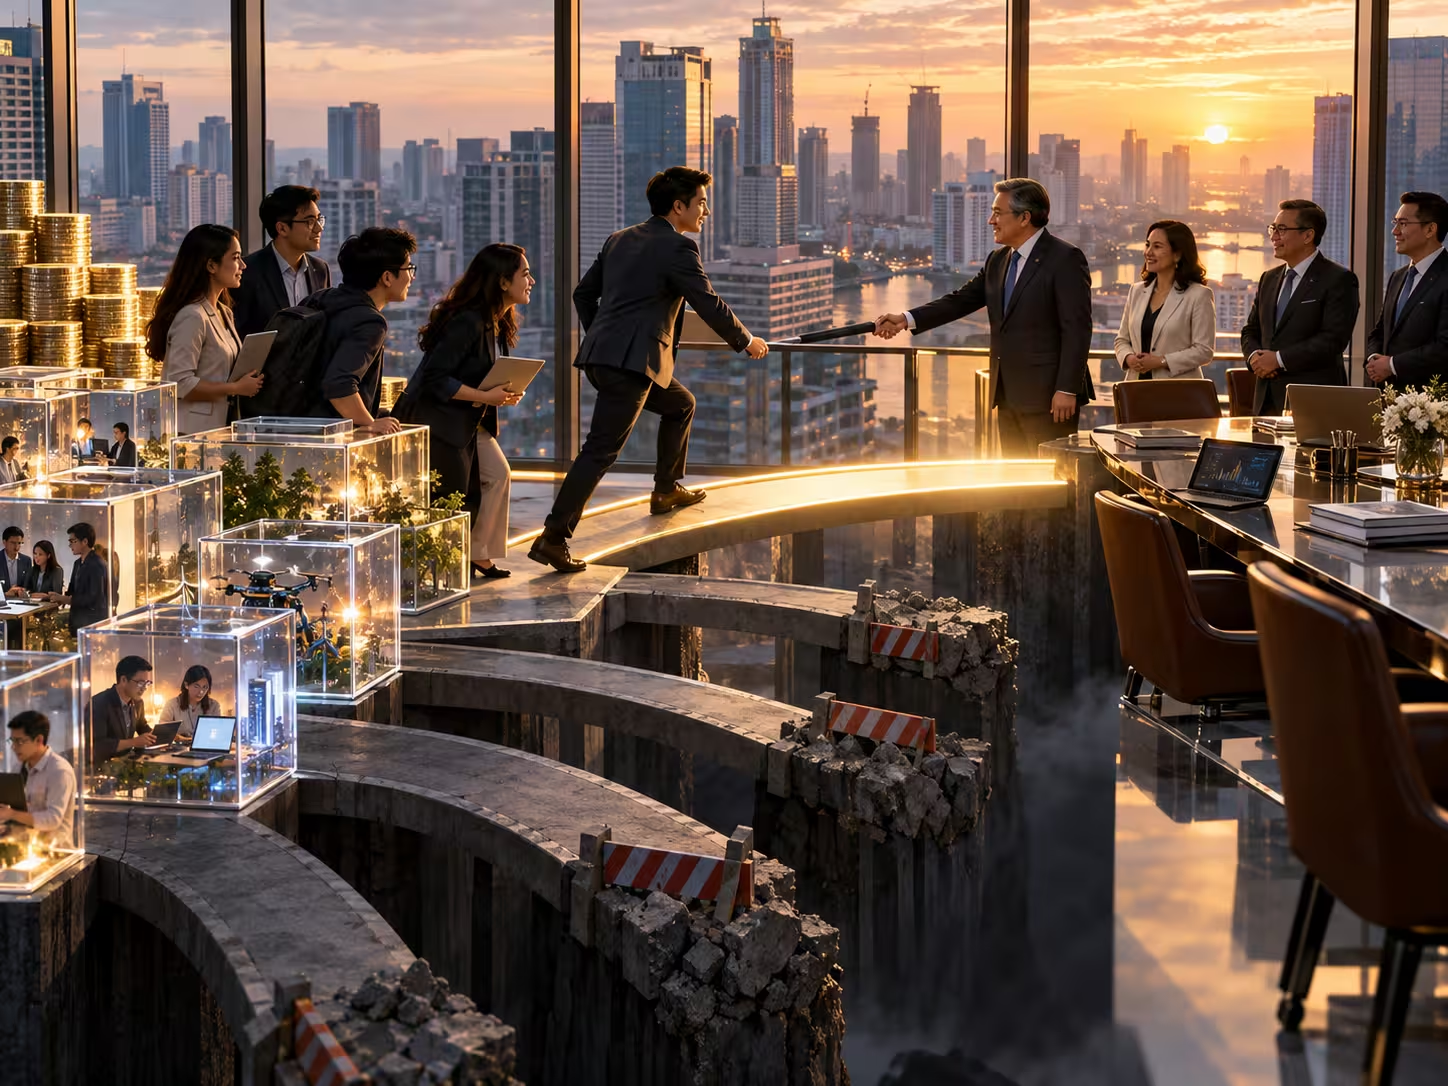
Succession in the Philippines is not only a management challenge. It is a legal and fiscal obstacle course, and the obstacles are written into the statute book. Estate tax remains at 6 percent, probate and estate administration impose practical burdens that can take years to resolve, and forced heirship rules limit how much discretion a founder has over the distribution of the estate.
For a family whose wealth is concentrated in an operating business, those rules create a specific and predictable problem: the heirs may inherit the enterprise, but they may not inherit the liquidity to pay the taxes attached to it.
The Liquidity Trap
An operating business is not cash. It is plant, inventory, receivables, and goodwill. When the founder dies, the estate’s tax liability is calculated on the value of the assets, not on the heirs’ ability to liquidate them. A family that owns a controlling stake in a mid-sized manufacturing firm or a regional retail chain can be asset-rich and cash-poor at precisely the moment the tax authority expects payment.
That mismatch forces heirs into decisions they would not otherwise make: selling a division, borrowing at unfavorable terms, bringing in outside investors, or liquidating assets that were meant to remain in the family. Each of those decisions can weaken the business at the exact moment it needs stability.
Reform on the Table
The policy environment is not static. A proposal filed in Congress would extend the estate tax amnesty to December 31, 2028, and some lawmakers have pushed further, proposing the outright abolition of estate tax at the time of death, with taxation shifted to the point of sale through capital gains tax. Another bill seeks to extend the amnesty period, reflecting sustained concern about the backlog of unsettled estates.
For family businesses, the significance of these proposals is not only the tax rate. It is the timing of the obligation. A tax collected at the point of sale, rather than at the point of death, would allow an enterprise to continue operating through the transition instead of forcing a distressed disposal to meet a fixed liability.
Forced Heirship and the Limits of Control
Philippine succession law also constrains the founder’s ability to design a clean handover. Forced heirship reserves a fixed portion of the estate for compulsory heirs, which means a founder cannot simply leave the business to the child who runs it while excluding the others. The result is often a fractured ownership structure in which active and inactive heirs hold competing claims on the same enterprise.
That structure is manageable when the family has planned for it—through a family constitution, a shareholder agreement, or a buy-sell arrangement that allows active heirs to acquire the shares of inactive ones over time. It becomes corrosive when the founder dies intestate or when the estate plan treats the business as just another asset to be divided equally.
The Advisory Gap
The legal complexity is compounded by a behavioral one. Many founders delay estate planning because it requires confronting mortality and because it surfaces uncomfortable questions about fairness among children. The consequence is that the most consequential legal decisions in a family business are often made by default rather than by design.
For Philippine families, the legal minefield is navigable—but only if it is mapped before the transition begins, not after the estate is already frozen.