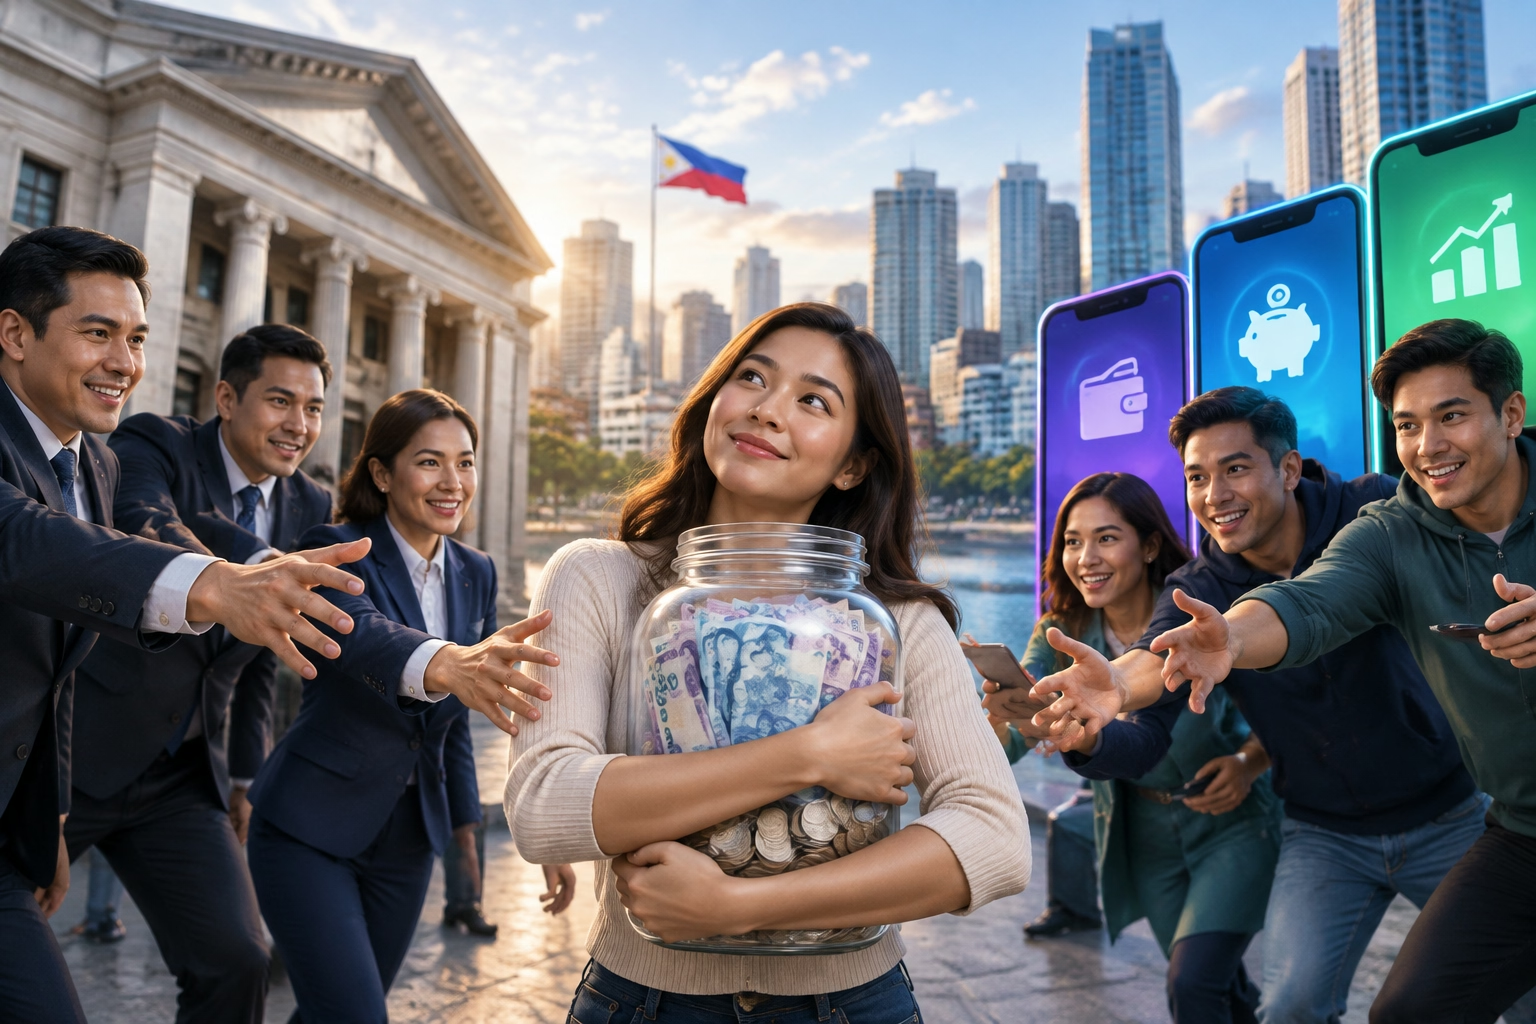
The fierce competition for deposits currently observed in the Philippine banking sector is not occurring in a vacuum. It is a direct consequence of the complex interplay between macroeconomic forces and monetary policy. To truly understand why banks are offering increasingly attractive interest rates in 2026, one must look at the signals being sent by the Bangko Sentral ng Pilipinas (BSP).
The central bank’s primary mandate is price stability. The tools it uses to achieve this—primarily the policy interest rate—have a profound impact on the banking sector’s cost of funds and, consequently, the rates offered to depositors.
The Policy Rate Transmission
When the BSP adjusts the RRP (Reverse Repurchase) rate, it sets the tone for the entire financial system. Banks generally adjust their deposit rates in tandem with the central bank’s movements.
If the BSP signals a higher policy rate to combat inflation, banks are incentivized to raise deposit rates to meet the higher benchmark. Conversely, a cut in the policy rate usually leads to a decline in deposit yields. However, 2026 presents a unique scenario where competition is preventing rates from falling as quickly as they might during a typical easing cycle.
Inflation and the Real Rate of Return
Inflation is the silent enemy of the depositor. If a bank offers a 4% interest rate but inflation is at 5%, the depositor is effectively losing money in real terms.
According to the latest inflation reports from the Philippine Statistics Authority (PSA), the rate of price increases has moderated compared to the peaks of 2023 and 2024, but remains a concern for policymakers. This environment forces banks to offer rates that provide a positive real return to attract savers. If banks offer rates lower than the inflation rate, savers are likely to pull their money out and put it into other assets like bonds, equities, or even real estate.
The Liquidity Coverage Ratio (LCR) Requirement
Regulatory compliance is another major factor driving competition. Under BSP regulations, banks must maintain a Liquidity Coverage Ratio (LCR)—a buffer of high-quality liquid assets to survive a short-term stress scenario.
Deposits are the cheapest and most reliable form of funding to meet these ratios. Therefore, banks compete aggressively for “sticky” deposits—funds that are likely to stay in the bank for a long duration.
- Wholesale vs. Retail: In 2026, we see banks competing for both retail deposits (from individuals) and wholesale deposits (from corporations and institutions). However, retail deposits are generally considered more stable, leading to a heavier focus on consumer-facing campaigns.
- Corporate Treasuries: On the other hand, corporate treasuries are moving their funds to the highest bidder, treating cash management as a profit center.
The Risk of Liquidity Mismatch
The intense competition also poses risks. To fund high-interest deposits, banks must lend at even higher rates. This can lead to a rise in borrowing costs for businesses and consumers, potentially slowing down economic activity.
Furthermore, if banks rely too heavily on hot money (short-term, rate-chasing deposits), they face the risk of a sudden outflow if a competitor offers a slightly better rate. This “stickiness” problem is a constant headache for bank treasurers in 2026.
The Outlook for 2026
Economic analysts suggest that while the competition will remain stiff, the trajectory of rates will heavily depend on the BSP’s next moves. If inflation continues to decelerate, the BSP may signal rate cuts. However, the banking sector’s need for liquidity to fund the country’s infrastructure and consumption boom suggests that the “war for deposits” will not cool down significantly in the immediate future.
For the savvy investor, understanding the BSP’s signals is the key to locking in the best rates before the tide turns.